Co-Signer Alert: How Parents on Title Can Cost You $4,000+
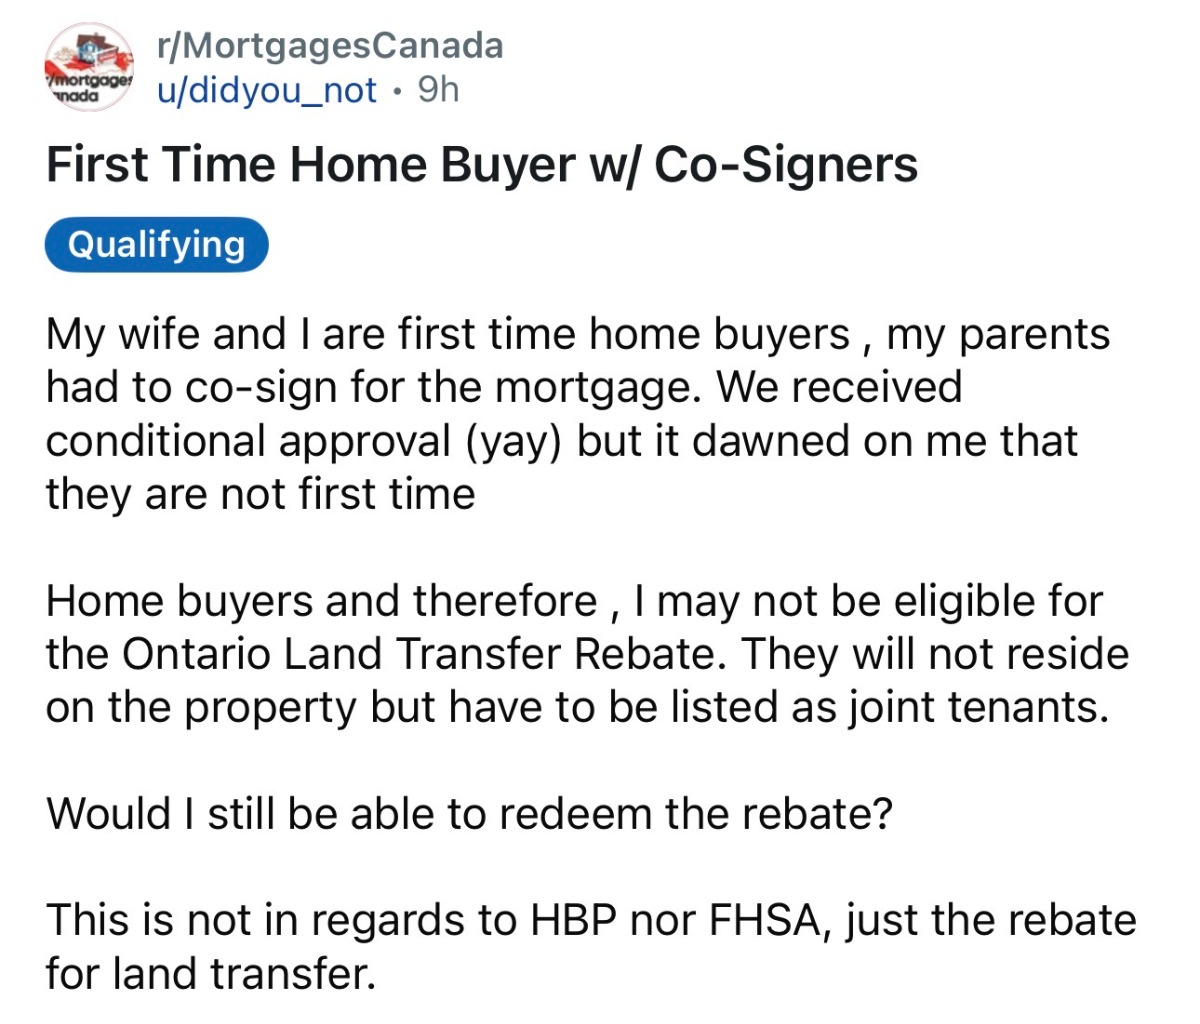
This couple are first-time buyers. Their parents co-signed the mortgage to help them qualify.
Now they're realizing:
If the co-signers aren't first-time buyers, we might lose the Ontario Land Transfer Tax rebate.
And they're right to be concerned.
Here's how the Land Transfer Tax rebate works in Ontario:
To qualify for the FIRST-TIME buyer rebate (up to $4,000):
- YOU must be a first-time buyer
- AND anyone else on title must ALSO be a first-time buyer
If your parents are on the mortgage for qualification purposes but will also be on TITLE (as joint tenants), they disqualify you from the rebate.
The fix:
Talk to your lawyer and lender about structuring this so:
- Parents are co-signers on the MORTGAGE (for income qualification)
- But NOT on TITLE (they don't have ownership interest)
This way, you keep your first-time buyer rebate.
But here's the real issue:
If your parents need to be on title because the lender requires it, you're in a tougher spot.
Some lenders allow co-signers without title; others don't.
This is a conversation that should have happened during PRE-APPROVAL, not at conditional approval.
What first-time buyers need to know:
Co-signers can help you qualify. But they come with trade-offs:
- Potential loss of rebates
- Your parents' credit is tied to this mortgage
- Family dynamics if something goes wrong
Always, always, always discuss co-signer implications with your mortgage agent AND lawyer BEFORE you go firm.
Thinking about using a co-signer?
Let's structure this properly from the start so you don't lose thousands in rebates.
Got other questions? You can book your free 15 MIN. MEETING call - no pressure, no sales pitch.
Just clarity.
Have a blessed week ahead!
Talk soon,
Fred Camingal
0 comments