You co-own 1% of your parents' house.
That tiny slice might be costing you thousands.
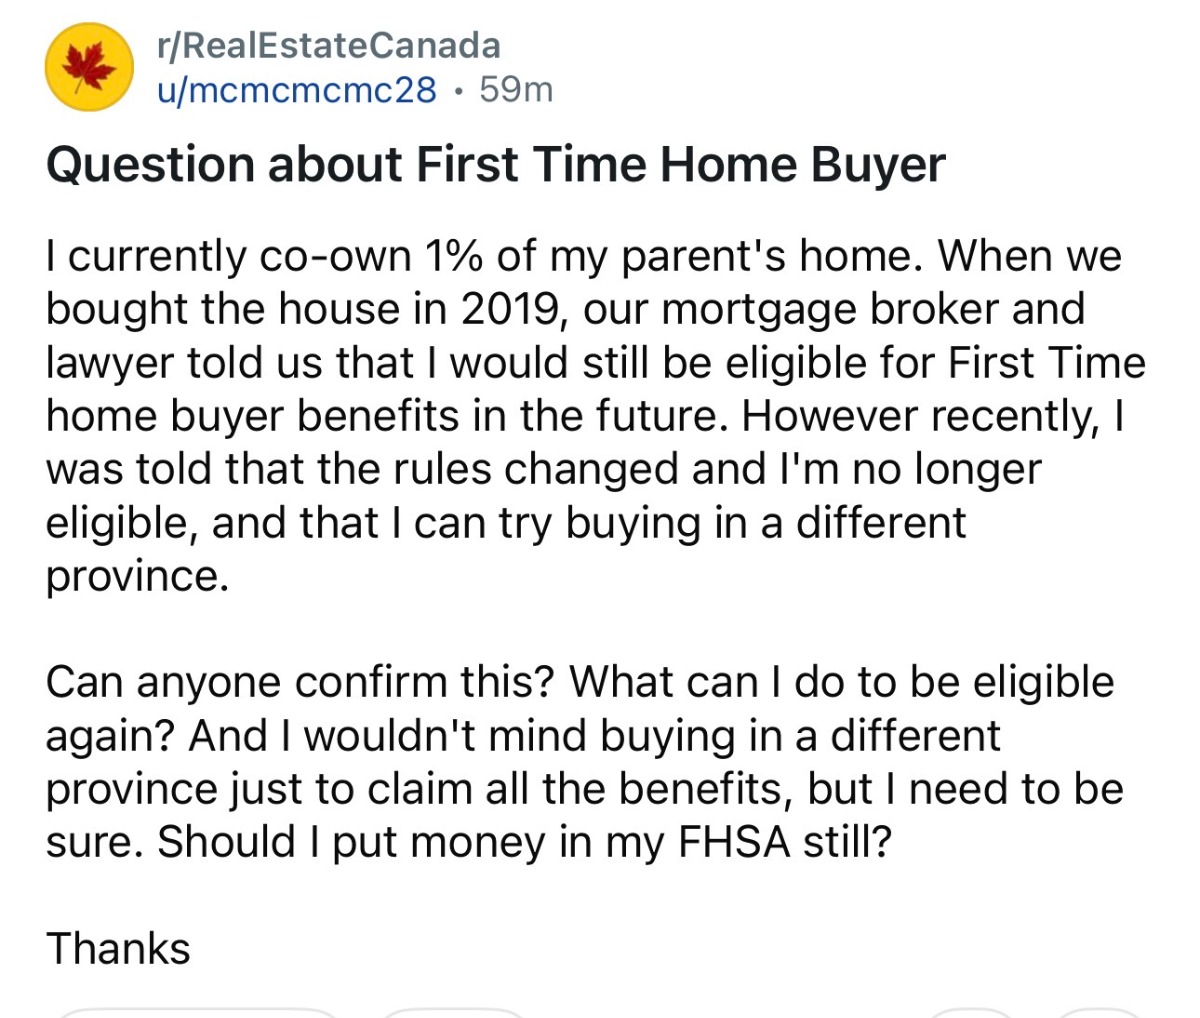
A first-time buyer just shared this on:
Back in 2019, they were added to their parents' mortgage as a co-owner (1% share) to help them qualify. Their mortgage broker AND lawyer both told them it wouldn't affect their FTHB status down the road.
Now? Someone's telling them the rules changed and they're no longer eligible.
Here's what is happening and this is important:
The rules haven't dramatically changed, but the interpretation matters.
For federal FTHB benefits (like the Land Transfer Tax rebate in Ontario and the Home Buyers' Plan), you generally cannot have owned a home in which you lived at any point in the preceding 4 years.
If you owned 1% of your parents' home but never used it as your principal residence then there's a reasonable case to be made that you still qualify for some benefits.
But here's where it gets nuanced:
The FHSA (First Home Savings Account) has its own eligibility criteria and yes, owning any residential property in the current year or any of the preceding 4 calendar years can disqualify you.
Province-specific rebates have their own rules.
"What your lawyer told you in 2019" doesn't automatically hold in 2025
Should you still contribute to your FHSA? Get confirmation from a tax professional first.
If you're disqualified and contributed anyway, you'll face penalties.
Buying in another province just to access benefits?
That's a workaround that can backfire badly so get legal advice before going down that road.
This is exactly the kind of thing that feels minor until it costs you $8,000 at closing.
DM me. Let's figure out where you actually stand.
#FirstTimeHomeBuyer #FHSA #HomesBuyerPlan #TorontoRealEstate #MortgageAdvice #firsttimehomebuyer #fredcamingal
______________________________
The "Phantom Cost" Home Buyers Always Forget — And Regret
You've saved your down payment. You've been pre-approved. You've found the one.
Then closing day hits — and nobody warned you about the $15,000–$25,000 in costs waiting quietly in the background.
Here's what too many first-time buyers in Toronto discover too late:
The purchase price is just the starting line.
Before you get the keys, budget for these often-overlooked closing costs:
- Land Transfer Tax — In Toronto, you pay both provincial and municipal. On a $800K home, that's roughly $24,000. First-timers get a rebate, but it only goes so far.
- Home Inspection — $500–$700. Non-negotiable. Don't let a hot market pressure you into skipping this.
- Title Insurance — ~$300–$500. Protects you from title fraud and errors. Worth every cent.
- Legal Fees — Budget $1,500–$2,500 for a real estate lawyer.
- Adjustments — Sellers often prepay property tax or utilities. You'll reimburse them at closing.
- Moving Costs + Immediate Repairs — The fridge that dies on day three doesn't care about your budget.
The rule of thumb: Set aside 1.5%–4% of your purchase price for closing costs, on top of your down payment.
The buyers who feel calm on closing day are the ones who planned for the full picture — not just the sticker price.
💬 Have questions about what to budget before your purchase? Reply to this email — I'm happy to walk you through the numbers.
_____________________________________
Got other questions? You can book your free 15 MIN. MEETING call - no pressure, no sales pitch.
Just clarity.
Talk soon,
Fred Camingal
0 comments